Is a 30-Year or 15-Year Mortgage Better for Me?
By Ron Cardozo, Sr. Home Loan Advisor, First Bank Mortgage | Overland Park, KS
30 years or 15 years? It's one of the simplest-sounding choices in your mortgage, and one of the most important.
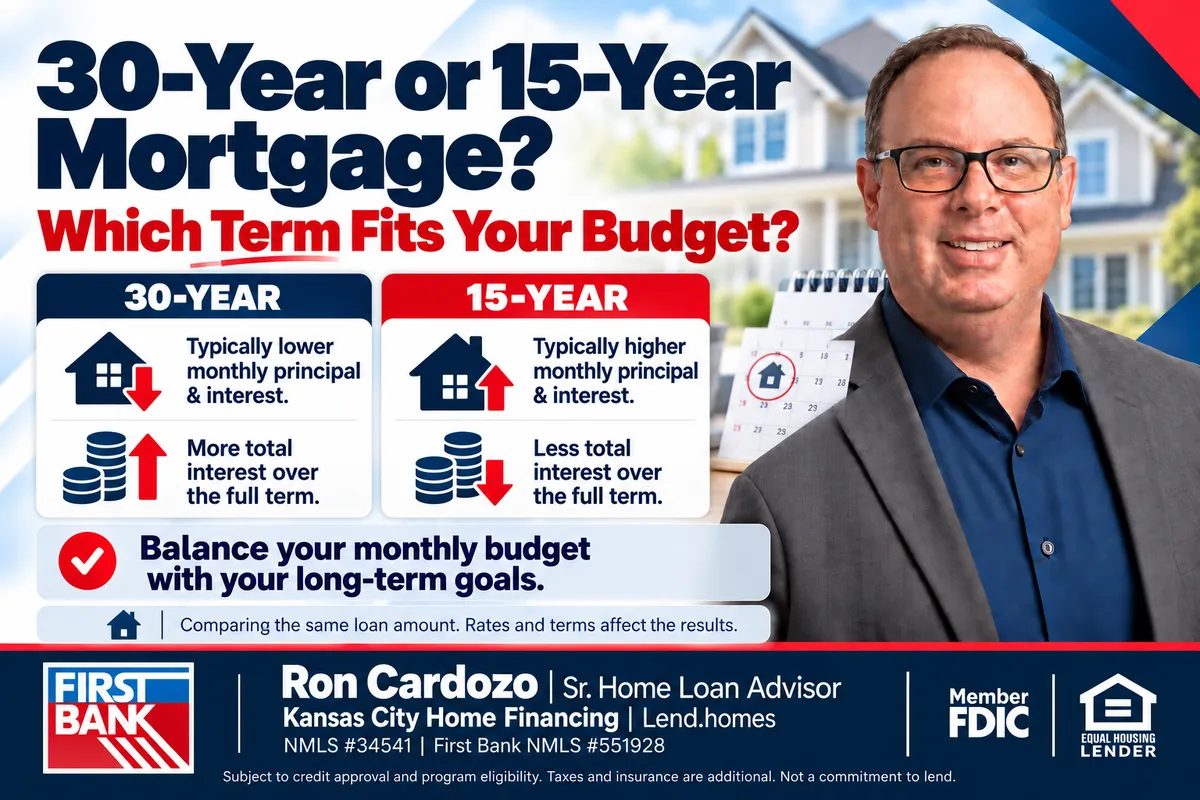
The trade-off is straightforward: a 15-year loan usually means a higher monthly payment, but much less interest paid over the life of the loan. A 30-year loan gives you a lower, more flexible payment, but you'll pay more interest over time.
The right answer depends on your budget, your goals and how you want your money working for you. Here's how to think it through.
30-Year vs. 15-Year at a Glance
| 30-year mortgage | 15-year mortgage | |
|---|---|---|
| Monthly principal and interest | Lower | Higher, since you're repaying the loan in half the time |
| Interest rate | Typically higher | Typically lower, sometimes by as much as a full percentage point |
| Total interest paid | Much more over the life of the loan | Much less over the life of the loan |
| Building equity | Slower, especially in the early years | Faster, since more of each payment goes to principal |
| Budget flexibility | More room for savings, emergencies and other goals | Less room each month |
| Paid off | In 30 years | In 15 years |
According to the CFPB, shorter terms save money in two ways: you pay interest for fewer years, and the rate is usually lower. Exactly how much you save, and how much higher the payment is, depends on your loan amount and the rates available when you apply.
Which Term Fits You?
A 30-year loan may be the better fit if you:
- Want the lowest required monthly payment
- Are a first-time buyer still building savings
- Want room in your budget for emergencies, retirement or college savings
- Have income that varies from month to month
- Need the lower payment to qualify for the home you want
A 15-year loan may be the better fit if you:
- Can comfortably afford the higher payment with room to spare
- Want to own your home free and clear sooner, such as before retirement
- Want to pay as little interest as possible
- Are refinancing and want to shorten your remaining term
- Want to build equity quickly
Most buyers choose a 30-year loan for its lower payment. But if a 15-year payment fits comfortably, the long-term savings can be significant.
You Have More Than Two Choices
It doesn't have to be all or nothing.
- Choose a term in between. Many lenders offer 20-year and 25-year loans, and the CFPB notes you can sometimes choose a custom term. A middle term can balance a manageable payment with real interest savings.
- Take a 30-year loan and pay extra. Extra principal payments reduce your balance faster and cut the total interest you pay. Unlike a 15-year loan, you can scale back to the regular payment if money gets tight. The trade-off is that a 30-year loan usually has a higher rate than a 15-year, so you won't save quite as much as the shorter term would.
- Shorten your term later. If your income grows, refinancing into a shorter term could be an option down the road, depending on rates and costs at that time.
Before planning extra payments, ask whether your loan has a prepayment penalty. I'll make sure you know.
Questions to Ask Yourself Before You Choose
- Could I comfortably afford the 15-year payment, with money left for savings and surprises?
- How long do I plan to stay in this home?
- What else do I want my money doing? Retirement, an emergency fund, paying off higher-interest debt or college savings may matter more right now.
- How steady is my income? If it varies, a lower required payment gives you breathing room.
- When do I want to be mortgage-free? If it's before a big life milestone like retirement, a shorter term may help you get there.
There's no wrong answer, only the one that fits your life best.
Frequently Asked Questions
Is the 15-year payment twice as much as the 30-year?
No. It's higher, but usually not double, because you're repaying the same amount in half the time and the rate is often lower. I'll show you the exact difference for your loan.
Is it harder to qualify for a 15-year loan?
It can be. The higher payment raises your debt-to-income ratio, so some buyers qualify for a larger loan with a 30-year term.
Can I pay off a 30-year loan in 15 years?
Often, yes, by making extra principal payments, as long as your loan has no prepayment penalty. You'll likely pay a bit more interest than with a true 15-year loan, because the 30-year rate is usually higher.
Does the loan term change my taxes and insurance?
No. Property taxes, homeowners insurance and HOA dues are the same either way. Only your principal and interest change.
Can I switch terms later?
You can refinance into a different term in the future, but that depends on rates, your home's value, your credit and closing costs at that time.
Let's Find the Right Term for You
I'll show you 30-year, 15-year and in-between options side by side, including your monthly payment and total interest for each, so you can pick the term that fits your budget and your goals.
Wondering whether a 30-year or 15-year loan is right for you? Call or text me.

Ron Cardozo | Sr. Home Loan Advisor
Call/Text: 913-710-5626
Email: [email protected]
Web: www.RonCardozo.com
Lend.homes: www.Lend.homes
About Ron: I've helped homebuyers in the mortgage industry since 1998 and am a Five Star Mortgage Professional award recipient. I serve the Kansas City metro on both sides of State Line and the Lake of the Ozarks, with an office at 6201 College Blvd, Suite 100, Overland Park, KS 66211. Lend.homes, Your Lender for Life.
First Bank Mortgage | NMLS #34541 | First Bank NMLS #551928 | Equal Housing Lender. This article is for general educational purposes only and is not a commitment to lend or an offer of credit. All loans are subject to credit approval, underwriting guidelines and property eligibility. Interest rates, payments and available loan terms vary by borrower, program and market conditions and may change without notice. Not all borrowers will qualify.
Sources: CFPB: Understand the different kinds of loans available · CFPB: Shopping for a mortgage · CFPB: Should I refinance?


