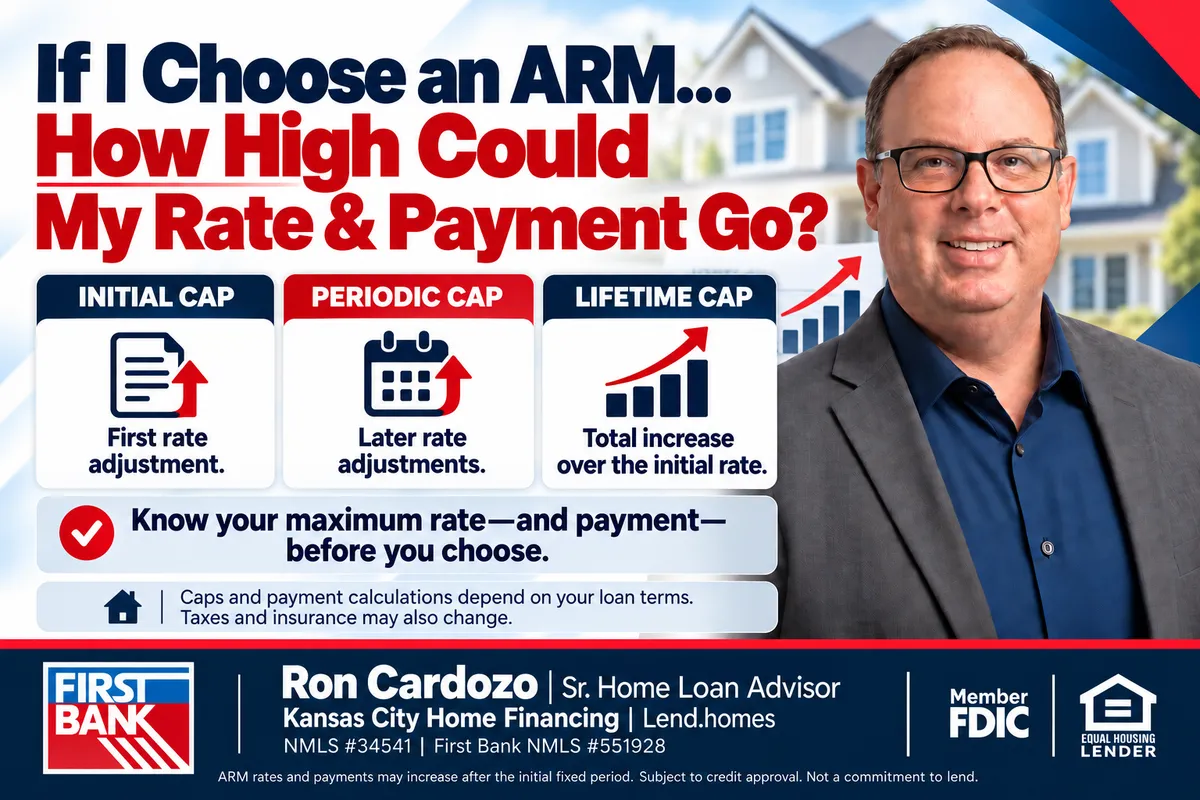
If I Choose an ARM, How High Could My Rate and Payment Go?
By Ron Cardozo, Sr. Home Loan Advisor, First Bank Mortgage | Overland Park, KS
With an adjustable-rate mortgage, the starting payment is only part of the story. The more important number is how high your payment could go.
The good news: your ARM comes with caps, which are limits on how much your interest rate can rise. Combined with the adjustment schedule, they tell you exactly how high your rate could ever go and how fast it could get there.
When you know those numbers, you can plan for the worst-case payment, not just the starting one. Here's how to find them.
The Three Caps That Limit Your Rate
Most ARMs have three kinds of caps. According to the CFPB, here's how they work and what's common:
| Cap | What it limits | Common amounts |
|---|---|---|
| Initial adjustment cap | How much the rate can change the first time it adjusts, after the fixed period ends | 2 or 5 percentage points |
| Subsequent adjustment cap | How much the rate can change at each adjustment after that | 1 or 2 percentage points |
| Lifetime cap | How much the rate can rise in total over the life of the loan, compared with your starting rate | Most commonly 5 percentage points; some loans allow more |
Some loans also have a floor, which is a limit on how low the rate can go. Not every ARM adjusts down as much as it can adjust up.
How to Read Cap Numbers and Find Your Maximum Rate
Caps are often written as three numbers in this order: initial / subsequent / lifetime. First Bank's portfolio 7/6 ARM and 10/6 ARM both use 5/1/5 caps, which means:
- The rate can change up to 5 points at the first adjustment
- Up to 1 point at each adjustment after that, which happens every 6 months
- Never more than 5 points above your starting rate
Your maximum rate = your starting rate + your lifetime cap, unless your loan documents list a different maximum.
Here's what that means in practice. Because the first-adjustment cap and the lifetime cap are both 5 points, your rate could reach its maximum at the very first adjustment. Shown as points above your starting rate:
| Point in the loan | 7/6 ARM (5/1/5 caps) | 10/6 ARM (5/1/5 caps) |
|---|---|---|
| Fixed period | Years 1 to 7: starting rate | Years 1 to 10: starting rate |
| First adjustment | Up to +5, the maximum (start of year 8) | Up to +5, the maximum (start of year 11) |
| Every 6 months after that | Can move up or down by up to 1 point at a time, never above +5 | Can move up or down by up to 1 point at a time, never above +5 |
The takeaway: with these loans, plan your budget around the maximum payment starting at the first adjustment, not a slow climb. The upside is a long fixed period of 7 or 10 years, which can be a strong fit if you expect to sell, refinance or pay down the loan before it adjusts.
Where to Find Your Worst Case on Your Loan Estimate
You don't have to calculate this alone. Every ARM Loan Estimate shows it in three places:
- Loan Terms (page 1). Next to your interest rate and principal and interest payment, it answers "Can this amount increase after closing?" For an ARM, it says how often the rate adjusts, when it starts, how high it can go, and the year it could first reach that maximum.
- Projected Payments (page 1). It shows a range of minimum and maximum payments for future years, so you can see what your payment could look like after adjustments.
- Adjustable Interest Rate (AIR) table (page 2). It lists your index, margin, minimum and maximum rate, when changes happen, and the limits on each change.
I'll walk you through all three, line by line, before you decide.
Stress-Test Your Budget
Before choosing an ARM, run this quick check:
- Find your maximum payment. Ask me for the principal and interest payment at your loan's maximum rate, and look at the highest payment in your Projected Payments table.
- Add the rest of your housing costs. Taxes, insurance, mortgage insurance and HOA dues can rise too.
- Compare it to your real budget. Use your take-home pay and everyday expenses, not just what you qualify for.
- Decide if you could live with it. If that payment would be a serious strain, a fixed rate or a smaller loan amount may be the safer choice.
Surprises to watch for, according to the CFPB's ARM handbook:
- Your rate can rise even if market rates don't. If your starting rate was lower than the index plus margin, it can climb at the first adjustment anyway.
- Carryover. On some loans, an increase held back by a cap can be added at a later adjustment, even if the index has stayed the same or fallen.
- Floors. When rates fall, your rate may not drop as far as you'd expect.
- Points may only help for a while. On an ARM, paying points often lowers your rate only during the initial fixed period.
One protection built in: lenders are generally required to consider your ability to repay based on the fully indexed rate (index plus margin) or the highest rate you could pay in the first five years, not just the introductory rate.
Frequently Asked Questions
What's the highest my ARM rate could ever go?
Usually your starting rate plus your lifetime cap. Your Loan Estimate's AIR table lists the exact maximum rate for your loan.
How quickly could my rate reach the maximum?
It depends on your caps. With First Bank's 7/6 and 10/6 portfolio ARMs and their 5/1/5 caps, the rate could reach its maximum at the first adjustment, right after the fixed period ends.
Could my payment go down instead?
It can, if the index falls. But some loans have a floor, and your rate may still rise at the first adjustment if your starting rate was below the index plus margin.
Will I get a warning before my rate changes?
Yes. Your loan servicer must notify you in advance of your first rate adjustment, which gives you time to plan or explore refinancing.
Are caps the same on every ARM?
No. Two ARMs with the same starting rate can have very different caps, so always compare caps, not just the starting rate.
Know Your Worst Case Before You Choose
An ARM can be a smart tool, as long as you go in knowing the highest your payment could ever be. I'll show you your caps, your adjustment schedule and your maximum payment side by side with a fixed-rate option, so there are no surprises later.
Considering an ARM and want to see your worst-case payment? Call or text me.

Ron Cardozo | Sr. Home Loan Advisor
Call/Text: 913-710-5626
Email: [email protected]
Web: www.RonCardozo.com
Lend.homes: www.Lend.homes
About Ron: I've helped homebuyers in the mortgage industry since 1998 and am a Five Star Mortgage Professional award recipient. I serve the Kansas City metro on both sides of State Line and the Lake of the Ozarks, with an office at 6201 College Blvd, Suite 100, Overland Park, KS 66211. Lend.homes, Your Lender for Life.
First Bank Mortgage | NMLS #34541 | First Bank NMLS #551928 | Equal Housing Lender. This article is for general educational purposes only and is not a commitment to lend or an offer of credit. All loans are subject to credit approval, underwriting guidelines and property eligibility. Adjustable-rate mortgage rates and payments may increase after the initial fixed period. Cap structures shown reflect First Bank portfolio 7/6 and 10/6 ARMs as of October 2026 and are subject to change; actual loan terms, caps, indexes and margins are disclosed on your Loan Estimate. Not all borrowers will qualify.
Sources: CFPB: Rate caps on adjustable-rate mortgages · CFPB: Consumer Handbook on Adjustable-Rate Mortgages · CFPB: Sample adjustable-rate Loan Estimate


