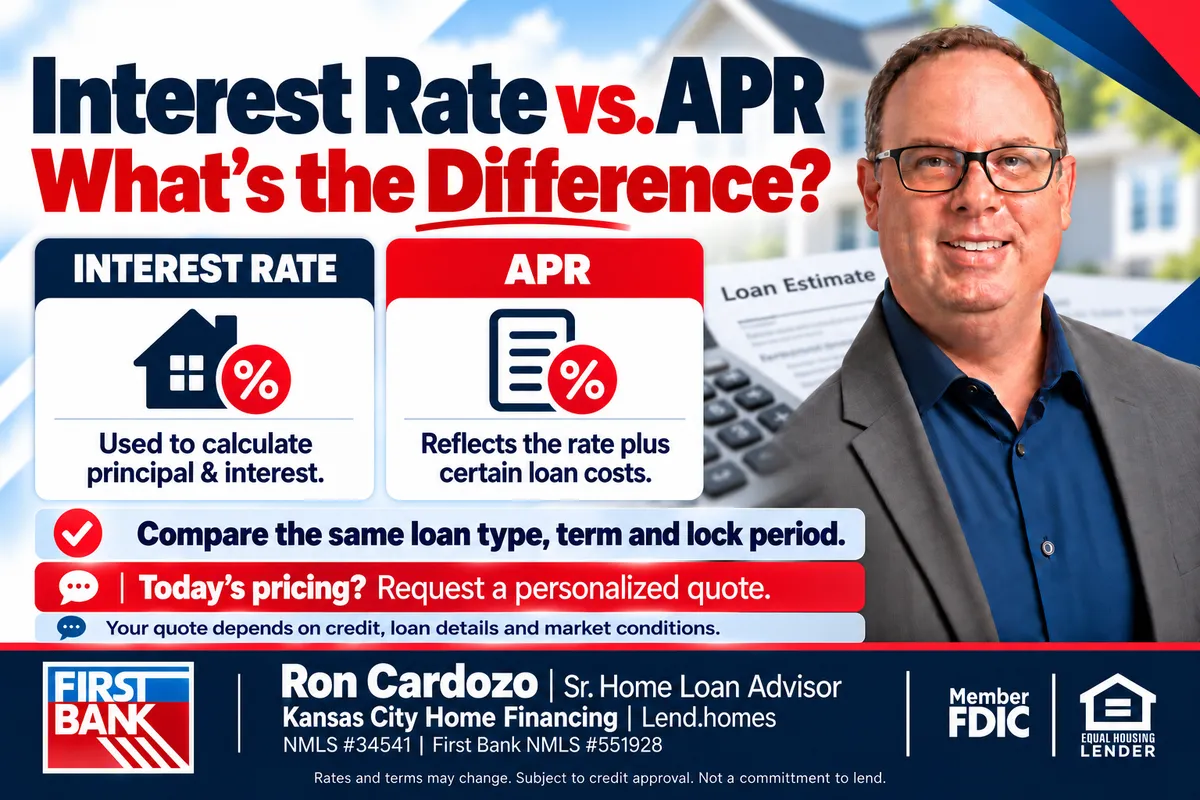
Interest Rate vs. APR: What's the Difference, and What Rate Can You Get Today?
By Ron Cardozo, Sr. Home Loan Advisor, First Bank Mortgage | Overland Park, KS
"What's your rate today?" It's usually the first question buyers ask. But the interest rate is only half of the answer.
Your interest rate sets your monthly principal and interest payment. Your APR (annual percentage rate) includes the interest rate plus certain fees you pay to get the loan. That's why comparing APRs side by side helps you see the true cost between lenders, not just who advertises the lowest rate.
Here's how the two differ, why there's no single "rate of the day" for everyone, and how to compare offers the right way.
Interest Rate vs. APR
| Interest rate | APR (annual percentage rate) | |
|---|---|---|
| What it measures | The yearly cost of borrowing the money | A broader yearly cost of borrowing |
| What it includes | Interest only, no fees | The interest rate plus points, mortgage broker fees and certain other charges you pay to get the loan |
| What it tells you | Your monthly principal and interest payment | The overall cost of the loan, for comparing offers |
| Which is higher | Usually lower | Usually higher, because it includes fees |
| Where to find it on your Loan Estimate | Page 1, under Loan Terms | Page 3, under Comparisons |
Source: CFPB
A quick way to read them together: if a loan's APR is much higher than its interest rate, that loan likely carries more upfront fees or points.
Why There's No Single "Rate Today"
Mortgage rates change daily, sometimes more than once a day, with the market. And the rate you're offered is personal. According to the CFPB, key factors include:
- Your credit score
- Your down payment and loan-to-value
- Loan type, such as conventional, FHA, VA or USDA
- Loan term, such as 30-year or 15-year
- Fixed or adjustable rate
- Loan amount and home price
- Property type and use, such as a primary home, second home or investment property
Points and lender credits also change your rate. You can pay discount points upfront for a lower rate, or accept a slightly higher rate in exchange for lender credits that reduce your closing costs. Neither is right for everyone. It depends on how long you plan to keep the loan.
A rate isn't yours until it's locked. Once you're under contract, a rate lock holds your rate for a set period, as long as nothing material about your loan changes.
So the honest answer to "What's your rate today?" is: let me price it for your situation. I'll show you real options based on your credit, down payment and loan choice, not a teaser rate.
How to Compare Lenders the Right Way
The best tool for comparing offers is the Loan Estimate, a standard three-page form every lender must give you after you apply. Because every lender uses the same form, you can line them up side by side.
- Request Loan Estimates on the same day if you can, since rates change daily.
- Ask for the same loan from each lender: same loan type, term, down payment and lock period.
- Compare the interest rate on page 1 to see your monthly payment.
- Compare the APR on page 3 to see the broader cost, including points and fees.
- Check the points on page 2. A lower rate that requires points isn't always the better deal.
- Compare total closing costs and cash to close, not just the rate.
Shopping for a mortgage within a short window has a limited effect on your credit, since multiple mortgage credit checks within 45 days are treated as one inquiry.
When the APR Can Mislead You
The APR is a great comparison tool, but it has limits. The CFPB cautions:
- ARMs: an ARM's APR doesn't reflect the maximum rate the loan could reach, so be careful comparing an ARM's APR to a fixed-rate loan's APR, or to another ARM's.
- HELOCs: a home equity line of credit's APR doesn't include fees, so don't compare it directly to a mortgage APR.
Two more things to keep in mind:
- APR spreads fees over the full loan term. If you expect to sell or refinance in a few years, a loan with lower upfront fees may cost you less, even if its APR is a bit higher.
- Not every cost is in the APR. Some closing costs, like certain title and third-party fees, aren't included. Always compare total closing costs and cash to close too.
Frequently Asked Questions
Why is my APR higher than my interest rate?
Because the APR includes points and certain fees on top of the interest. That's normal.
Should I always choose the loan with the lowest APR?
Not always. The lowest APR often fits best if you'll keep the loan a long time. If you might sell or refinance soon, compare upfront costs too.
Can you tell me my exact rate over the phone?
I can give you a general idea, but your actual rate depends on your credit, down payment and loan details. A quick application lets me price your real options and give you a Loan Estimate.
What are discount points?
An upfront fee you can pay at closing in exchange for a lower interest rate. They can make sense if you plan to keep the loan for many years.
When should I lock my rate?
Typically once you're under contract on a home. We'll talk through timing together based on your closing date and the market.
Let's Price Your Real Options
Instead of a teaser rate, I'll give you real numbers for your situation: your rate, your APR, your points and your total closing costs, side by side for each loan option. That way you can compare with confidence.
Want to know what rate and APR you could get today? Call or text me.

Ron Cardozo | Sr. Home Loan Advisor
Call/Text: 913-710-5626
Email: [email protected]
Web: www.RonCardozo.com
Lend.homes: www.Lend.homes
About Ron: I've helped homebuyers in the mortgage industry since 1998 and am a Five Star Mortgage Professional award recipient. I serve the Kansas City metro on both sides of State Line and the Lake of the Ozarks, with an office at 6201 College Blvd, Suite 100, Overland Park, KS 66211. Lend.homes, Your Lender for Life.
First Bank Mortgage | NMLS #34541 | First Bank NMLS #551928 | Equal Housing Lender. This article is for general educational purposes only and is not a commitment to lend, an offer of credit or a rate quote. All loans are subject to credit approval, underwriting guidelines and property eligibility. Interest rates and APRs vary by borrower, loan program and market conditions and change daily. Rates are not guaranteed until locked. Not all borrowers will qualify.
Sources: CFPB: Interest rate vs. APR · CFPB: Seven factors that determine your mortgage interest rate · CFPB: Loan Estimate explainer


