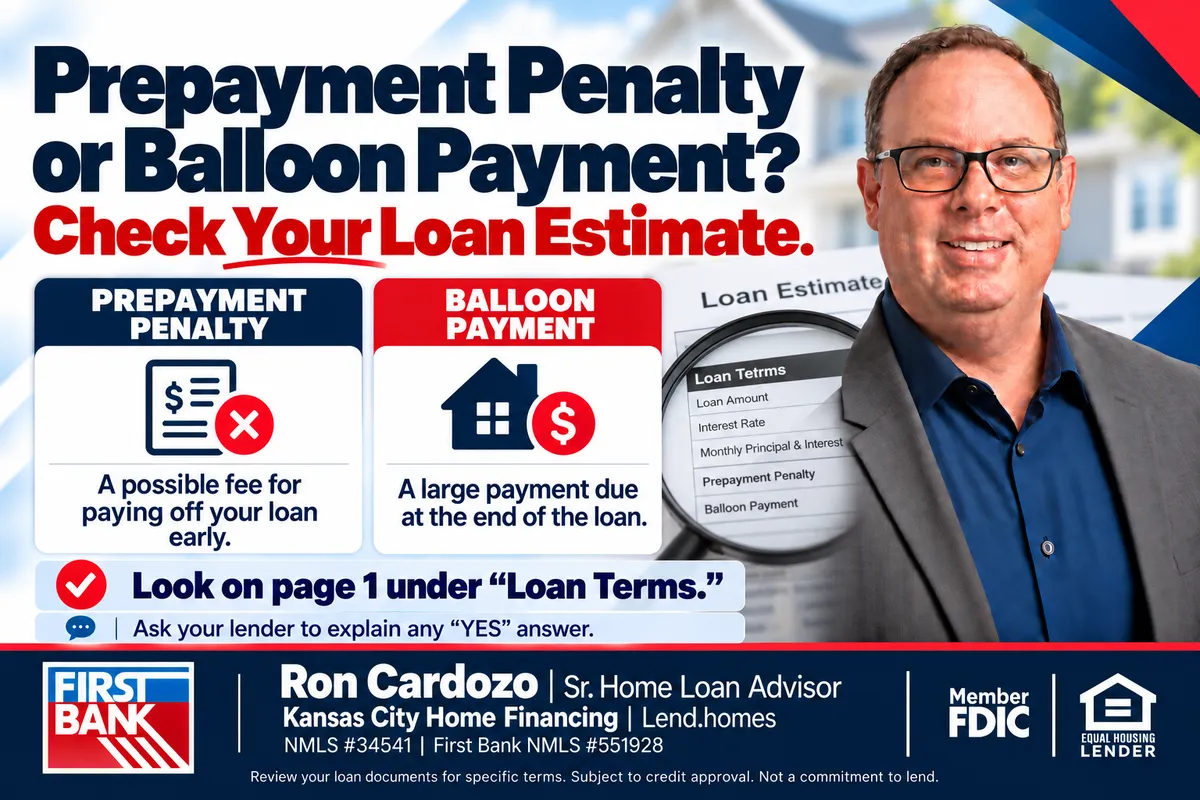
Does This Loan Have a Prepayment Penalty or a Balloon Payment?
By Ron Cardozo, Sr. Home Loan Advisor, First Bank Mortgage | Overland Park, KS
Most buyers focus on the rate and the payment. But two other loan features can cost you a lot if you don't spot them: a prepayment penalty and a balloon payment.
The Consumer Financial Protection Bureau calls both features risky. One charges you for paying off your loan early. The other leaves a large lump sum due at the end.
The good news: they're easy to check for, and most of today's home loans don't have them. Here's what to look for and what to ask.
Prepayment Penalty vs. Balloon Payment
| Prepayment penalty | Balloon payment | |
|---|---|---|
| What it is | A fee the lender can charge if you pay off your mortgage early | A final payment that's much larger than your regular monthly payments |
| When it hits | If you sell, refinance or pay the loan off early, usually within the first few years | At the end of the loan term |
| Why it's risky | It can make selling or refinancing more expensive, even when it would otherwise save you money | You may need to come up with a large lump sum, or refinance or sell, when it comes due |
| What to look for | "Prepayment Penalty: YES" in the Loan Terms section | "Balloon Payment: YES" in the Loan Terms section |
Either one can turn a loan that looks affordable today into a costly surprise later.
Where to Find Them on Your Paperwork
You don't have to dig through fine print. Both features are disclosed on page 1 of your Loan Estimate and your Closing Disclosure, in the Loan Terms section.
Look for two lines:
- Prepayment Penalty: "NO" means you can pay off your loan early without a penalty. "YES" means there's a penalty, and the form shows how much and for how long.
- Balloon Payment: "NO" means your regular payments pay off the loan. "YES" means a large lump sum is due, and the form shows the amount and when.
Check these lines on your Loan Estimate when you apply, then again on your Closing Disclosure before you sign, to make sure nothing changed.
Federal Rules Limit Both
After the 2008 housing crisis, federal mortgage rules put strict limits on these features for most home loans, according to the CFPB:
Prepayment penalties are banned on most home loans. They're allowed only on certain fixed-rate "qualified mortgages" that aren't higher-priced, and even then:
- No penalty after the first three years
- No more than 2% of the balance prepaid in the first two years, and 1% in the third year
- The lender must also offer you a comparable loan with no prepayment penalty, so you can choose
Balloon payments are generally not allowed on "qualified mortgages." The main exception is for certain small lenders operating in rural or underserved areas, under specific conditions.
That's why most standard home loans today, including conventional, FHA, VA and USDA loans, typically don't have either feature. They're more likely to show up on some specialty, investor or non-standard loans, which is exactly why it's worth checking every time.
Questions to Ask Your Lender
- Does this loan have a prepayment penalty? If yes, how much is it, and for how long?
- Does the penalty apply if I sell the home, or only if I refinance?
- Can I make extra principal payments without a penalty?
- Does this loan have a balloon payment? If yes, how much, and when is it due?
- What happens if I can't refinance or sell before the balloon payment is due?
- Is there a comparable loan without these features, and how do the costs compare?
If the answers aren't clear, ask again. You should understand exactly how your loan ends before you sign.
Frequently Asked Questions
Do most mortgages have a prepayment penalty?
No. Federal rules ban them on most home loans and strictly limit them on the few where they're allowed. But always check the Loan Terms section to be sure.
Is paying extra each month considered prepaying?
Yes, extra principal payments are a form of prepayment. On loans without a prepayment penalty, you can pay extra anytime. If your loan does have one, ask how it applies to partial payments.
Is a balloon payment the same as an ARM adjustment?
No. An ARM's payment can rise when the rate adjusts, but the loan still pays off over its term. A balloon loan leaves a large lump sum due at the end.
Why would anyone choose a loan with these features?
Sometimes they come with a lower rate or fit a specific situation, like a short-term or specialty loan. If a lender offers one, compare it to an option without the feature so you know what you're trading.
What if my Closing Disclosure shows "YES" when my Loan Estimate said "NO"?
Don't sign until you get a clear explanation. Ask your lender why it changed and what your options are.
Know Exactly What You're Signing
I'll walk you through every line of your Loan Estimate and Closing Disclosure, including the Prepayment Penalty and Balloon Payment lines, so you know exactly how your loan works from the first payment to the last.
Have questions about the terms of your loan? Call or text me.

Ron Cardozo | Sr. Home Loan Advisor
Call/Text: 913-710-5626
Email: [email protected]
Web: www.RonCardozo.com
Lend.homes: www.Lend.homes
About Ron: I've helped homebuyers in the mortgage industry since 1998 and am a Five Star Mortgage Professional award recipient. I serve the Kansas City metro on both sides of State Line and the Lake of the Ozarks, with an office at 6201 College Blvd, Suite 100, Overland Park, KS 66211. Lend.homes, Your Lender for Life.
First Bank Mortgage | NMLS #34541 | First Bank NMLS #551928 | Equal Housing Lender. This article is for general educational purposes only and is not a commitment to lend or an offer of credit. All loans are subject to credit approval, underwriting guidelines and property eligibility. Loan features, including any prepayment penalty or balloon payment, are disclosed on your Loan Estimate and Closing Disclosure and vary by loan program. Federal rules summarized here may change. Not all borrowers will qualify.
Sources: CFPB: Closing Disclosure explainer · CFPB: Loan Estimate explainer · CFPB: Ability-to-Repay and Qualified Mortgage Rule guide


