TRANSPARENT FINANCING
What Will My Payment
Actually Be?
Most online calculators give you an incomplete number that leaves out taxes, insurance, and local fees. We break down the real anatomy of your monthly mortgage so you can make your dream move with zero surprises.
100% Free · No credit check required · Unbiased financial analysis
PAYMENT ANATOMY
The Six Components
Of Your Payment
A standard mortgage check rarely covers just the loan. Understanding each independent piece prevents budget surprises and helps you track what builds real equity versus ongoing ownership overhead.
CORE LOAN • 01
Principal
The original loan amount you borrowed to purchase the home. Every dollar applied here directly reduces your outstanding balance and accumulates tangible home equity.
LENDER FEE • 02
Interest
The financial charge levied by the mortgage lender for borrowing their funds. During early loan years, interest represents the majority of your scheduled payment.
GOVERNMENT • 03
Property Taxes
Taxes assessed by county and municipal governments to fund local schools, roads, and emergency services. Often collected monthly into an escrow reserve.
PROTECTION • 04
Homeowners Insurance
Hazard coverage shielding the physical structure and personal property from perils like fire, storm damage, or theft. Mandatory by all mortgage lenders.
RISK MITIGATION • 05
Private Mortgage Insurance
Typically required if putting less than 20% down. PMI safeguards the lender against default risk and automatically cancels once you hit 20% to 22% home equity.
COMMUNITY • 06
HOA Assessments
Monthly or quarterly dues paid to condo or neighborhood associations for shared amenities, exterior maintenance, and community reserve funds.
CASE STUDY: $400,000 PURCHASE
A Real-World
Breakdown
Mortgage calculators quote the principal and interest sticker price of $2,275/mo. Here is how mandatory escrows, reserves, and dues convert that baseline into an actual $3,200 monthly commitment.
Monthly Housing Expense
PROTECTIVE FINANCIAL FORECASTING
Beware The Hidden
Increases
Most generic online calculators assume your closing payment remains completely locked in stone for thirty years. In truth, your fixed principal and interest stay static, but your surrounding escrow and community assessments frequently shift within eighteen months of ownership.
When a county reassesses your home to match its fresh purchase price, past tax exemptions disappear and the tax bill resets upward. If your loan servicer was under-collecting, you face both a higher forward tax payment and a one-time escrow shortage fee.
- Purchase-price county tax reassessments reset legacy exemptions
- Condo or subdivision reserve deficits trigger mandatory special dues
- Annual insurance renewals fluctuate with regional climate claims
Our Advisory Promise: We stress-test your monthly housing budget against a minimum 15% escrow buffer so you are never blindsided by year two adjustments.
Safety Note: Tax Reassessment Gap
The prior homeowner may have lived there for 20 years with capped tax assessments or senior freeze credits. Upon sale, the tax assessor recalibrates the property to current market value, frequently driving tax bills up $150 to $400 monthly.
Advisory Recommendation: Never budget around the seller's historical tax rate. Always calculate millage rates against your agreed contract purchase price.
Safety Note: HOA Special Assessments
When a condominium association or planned development fails to maintain adequate capital reserves for roofs, elevators, or structural repairs, regular dues are suddenly supplemented by emergency special assessments reaching thousands per door.
Advisory Recommendation: Mandate a rigorous review of the association reserve study and last 24 months of board meeting minutes before lifting inspection contingencies.
STEP-BY-STEP VERIFICATION
Get An Accurate
Estimate Before Buying
Eliminate budgeting blindspots before you make an offer. Follow this three-phase protocol to calculate taxes, insurance premiums, and lender fees with complete clarity.
STAGE 01
1. Review Listing Details
Uncover hidden property covenants, special tax assessments, and mandatory community fees before factoring them into your purchasing budget.
- Audit annual HOA dues and transfer assessments
- Verify county millage rates vs listed estimates
- Check municipal parcel boundary records
STAGE 02
2. Get Insurance Quotes
Never rely on national insurance averages. Secure binding quotes directly from underwriters factoring in roof age, flood maps, and regional peril.
- Compare hazard rates across multiple independent brokers
- Check FEMA Special Flood Hazard Area designations
- Determine windstorm or wildfire surcharge tiers
STAGE 03
3. Request Loan Estimate
Obtain standard federal Loan Estimate disclosures from competitive lenders to compare true APR, origination points, and pre-paid escrow terms.
- Scrutinize Section A lender fees and origination points
- Examine initial escrow buffer deposits for taxes and insurance
- Confirm rate lock expiration and float-down policies
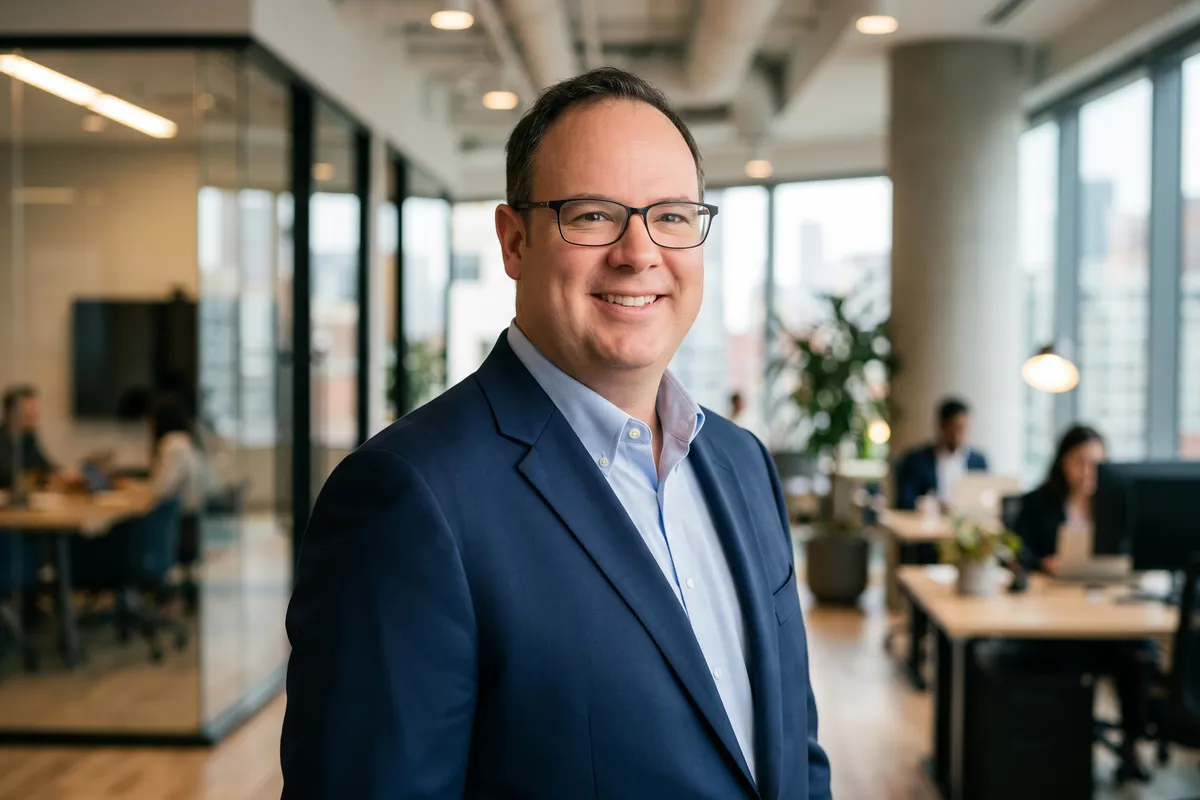
Ron Cardozo : Senior Home Loan Advisor (NMLS #34541)
"My mission is never to push maximum borrowing capacity. It is to calculate your exact taxes, insurance, and HOA fees so you never face a post-closing surprise."
ZERO-PRESSURE CONSULTATION
Get Your True
Estimate Today
Leave automated estimator guesses behind. Share a few home parameters and we will run custom calculations with verified local property taxes, insurance estimates, and HOA requirements.