MORTGAGE EDUCATION
Will Checking My Credit Hurt My Score?
The short answer is no. Discover the truth about soft vs. hard inquiries and protect your financial health.
100% Free · No Impact on Your Credit Score · Instant Access
MORTGAGE CREDIT EDUCATION
The Most Persistent Myth in Real Estate
Every year, thousands of qualified prospective home buyers freeze right when they should be preparing. They avoid checking their own credit reports or reviewing their credit scores out of a deeply ingrained fear: the belief that simply looking at your own numbers will instantly damage them.
The definitive truth is straightforward: checking your own credit never penalizes your score. When you log in to an authorized monitoring tool, access your bank's portal, or request your official annual report, credit reporting bureaus categorize that action strictly as a soft inquiry. It is entirely invisible to lenders and mathematically incapable of reducing your score by even a fraction of a point.
Operating without knowledge does far more harm than review ever could. Unchecked errors, outdated collections, or identity mismatches linger indefinitely when buyers delay. By taking full ownership of your credit profile early, you establish control, identify reporting inaccuracies, and build genuine leverage before ever submitting a formal mortgage application.
“Fear of a score drop keeps too many buyers in the dark.”
Mortgage Advisory Insight
First Bank Consultation Team
INQUIRY COMPARISON MATRIX
Soft Pulls vs. Hard Pulls
Understanding exactly how each credit inquiry type is categorized by the major bureaus removes uncertainty and protects your mortgage readiness.
NO CREDIT SCORE IMPACT
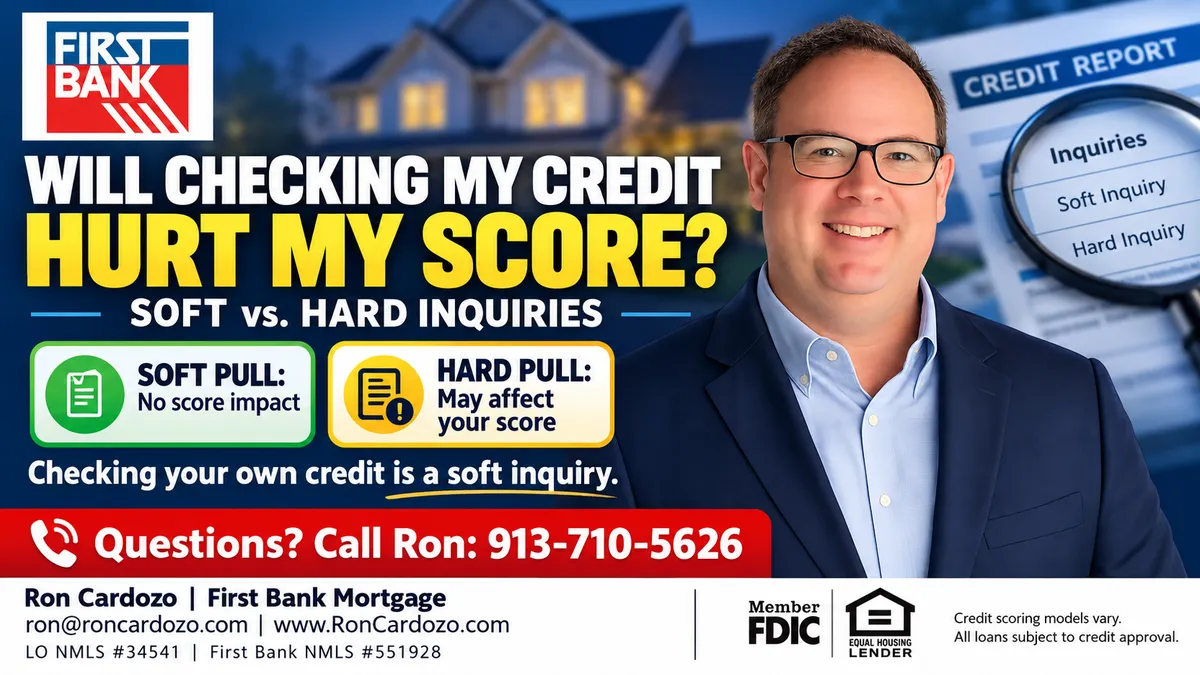
Soft Inquiry
A routine background review performed for informational purposes. It does not indicate an application for new credit lines and carries zero score consequence.
- 0 points lost: completely harmless to your FICO and VantageScore models
- Invisible to external lenders, underwriters, and banking institutions
- Visible solely on your personal consumer-disclosure credit report
- Applies to pre-qualified loan estimates, monitoring apps, and employer screens
TEMPORARY 3–5 POINT ADJUSTMENT
Hard Inquiry
Triggered when you submit a formal financing application. The financial institution pulls your full file from Equifax, Experian, or TransUnion for underwriting.
- Minor temporary drop: usually 3 to 5 points off your overall score
- Fully visible to all lenders reviewing your tri-merge credit report
- Points typically rebound within 60 to 90 days of normal payment activity
- Remains on report for 24 months, but affects score calculation for only 12 months
Key Takeaway: A pre-qualification consultation with Ron Cardozo starts with a soft inquiry that will never harm your score. Even when a hard inquiry is later required for final loan commitment, its 3–5 point dip is negligible and easily absorbed.
CREDIT REPORTING ACCURACY & BORROWER RIGHTS
The Rate Shopping Advantage
1 in 5
consumers have an error on their credit report.
BORROWER PROTECTION WINDOW
Multiple Mortgage Inquiries in a 14 to 45-Day Window Count as a Single Hard Pull
Under standard FICO and VantageScore scoring models, multiple mortgage applications submitted within a 14 to 45-day shopping window are bundled and scored as exactly one inquiry. Lending formulas recognize that prudent buyers shop for the best rate. Comparing offers across several financial institutions will not compound score penalties or threaten your mortgage approval standing.
Shop with confidence: Comparing mortgage terms is legally protected and safe for your credit profile.
PRE-MORTGAGE BLUEPRINT
4 Steps to Prepare Your Credit
Follow this strategic four-point protocol 60 to 90 days before your mortgage pre-approval to ensure optimal loan terms and pricing.
01
ANNUALCREDITREPORT.COM
Pull All 3 Bureau Reports
Access your official, federally mandated free consumer credit files from Equifax, Experian, and TransUnion via AnnualCreditReport.com with zero score penalty.
02
DISPUTE RESOLUTION
Review Thoroughly for Errors
Inspect line-by-line for misreported late payments, incorrect balances, or phantom accounts. File prompt disputes with bureaus to clear discrepancies well before underwriting.
03
UTILIZATION RATIOS
Pay Down Balances Substantially
Drive revolving credit card balances below 30% of their limits, ideally under 10%. Revolving debt utilization represents nearly a third of your scoring model.
04
PORTFOLIO STABILITY
Avoid Opening New Accounts
Refrain from financing vehicles, taking out personal loans, or applying for retail store cards. New lines lower average account age and create unforced hard inquiries.
DIRECT CONSULTATION & GUIDANCE
Get a Clear Picture of What You Qualify For
Credit education is only the foundation. When you are ready to explore your purchasing power or review your financing readiness, Ron is here to walk you through every nuance with complete transparency and zero guesswork.
First Bank Senior Loan Officer • Individual NMLS #: 34541
Ron Cardozo
Senior Home Loan Advisor
Personal guidance for your home financing goals.
Get in Touch
Fax: (913) 712-0307
First Bank, 6201 College Blvd., Suite 100
Overland Park, KS 66211
Let’s Connect
Have questions about buying a home or refinancing? Contact Ron to discuss your financing options.
Ron Cardozo | LO NMLS ID: 34541
First Bank | NMLS ID: 551928
Equal Housing Lender. Member FDIC.
All loans are subject to credit approval and property eligibility. This is not a commitment to lend. Programs, terms, and conditions are subject to change without notice.
© October 10th 2026 First Bank. All Rights Reserved. | Privacy Policy | Terms of Service