Ron Cardozo NMLS #34541 • First Bank NMLS #551928
Call Direct: (913) 710-5626
LICENSED IN ALL 50 STATES • NMLS #34541
Your Nationwide
Home Loan Expert
Navigating mortgages doesn't have to feel daunting. Combining decades of institutional banking strength with accessible, individualized guidance, Ron Cardozo delivers transparent loan options tailored to your family's future across all 50 states.
No obligation • Soft credit inquiry • Same-day pre-approval letters
First Bank Reliability — Backed by full underwriting authority, rapid loan turnarounds, and competitive national pricing.
★ NATIONWIDE EXPERT
Ron Cardozo
Senior Loan Officer • First Bank
NMLS #34541 | First Bank NMLS #551928
Direct cell with personal consultation • No call center wait
SPECIALIZED LENDING PILLARS
Tailored Solutions
For Every Goal
Mortgage financing is rarely one-size-fits-all. Every borrower, balance sheet, and market timeline presents unique constraints. Ron crafts bespoke loan architecture across all fifty states, delivering institutional backing with concierge-level precision from day one.
PILLAR 01 // FIRST-TIME & MOVE-UP BUYERS
Home Buyers & Relocation
Purchasing a home demands aggressive speed and clear terms. Ron structures personalized Conventional, FHA, VA, and Jumbo loan packages designed to make your offer stand out in competitive bidding environments.
- Custom down payment roadmaps and grant program matching
- Full pre-underwritten approvals that sellers trust
- Lock-and-shop protections against volatile rate swings
PILLAR 02 // RATE & EQUITY OPTIMIZATION
Current Homeowners (Refinance)
Put your accumulated home equity to work. Whether you are aiming to lower your monthly commitment, consolidate high-interest debt, or finance major property additions, Ron outlines mathematically validated scenarios.
- Cash-out equity options for strategic family milestones
- Term adjustments to compress total lifetime interest
- PMI removal calculations with current market valuation analysis
PILLAR 03 // AGENT SUCCESS & CERTAINTY
Real Estate Agents & Brokers
Partner with a lending specialist who treats your reputation like his own. Ron provides open-book status tracking, direct weekend phone availability, and bulletproof qualification letters that protect transaction timelines.
- Reliable 7-day milestone alerts to all parties in the deal
- Saturday and Sunday pre-approval desk for live offer writing
- Strict on-time closing record with dedicated processing queues
SENIOR LOAN OFFICER
A Personal Touch
To Traditional Banking
In an era of automated portals and generic algorithms, securing your home financing shouldn't feel like submitting a ticket into a digital void. As a Senior Loan Officer backed by the regional balance sheet and stability of First Bank, my commitment is grounded in understanding your family's long-term milestones before running numbers.
Whether you are navigating your first purchase or coordinating a high-equity transition, you work directly with me—from initial scenario planning to the closing table. You get the peace of mind of institutional banking, elevated by the sincere, personal partnership you deserve.
Ron Cardozo NMLS #34541 | First Bank NMLS #551928
 MORTGAGEBUILT FOR WHAT'S NEXT.

Seller concessions, explained
Seller Buydown Comparison
Four ways a seller credit can lower a buyer's rate, side by side. Change any number below and every option recalculates.

Same seller dollars, two ways to spend them
Monthly payment drop for the buyer when the seller funds the buydown, compared with cutting the price by the same amount.
Option details
Principal and interest on a 30-year amortization. Payments do not include taxes and insurance.
How a rate buydown works
A buydown is money paid at closing to lower the buyer's interest rate, which lowers their monthly payment. Sellers often pay for it as a concession instead of, or in addition to, cutting the price.
Temporary buydown
The rate is reduced for the first one to three years, then returns to the full note rate.
- 3/2/1: 3% lower in year 1, 2% lower in year 2, 1% lower in year 3, full rate from year 4.
- 2/1: 2% lower in year 1, 1% lower in year 2, full rate from year 3.
- The seller's cost equals the buyer's total payment savings during those early years. That money goes into an escrow account at closing and covers the difference each month.
Permanent buydown
The buyer's rate is lowered for the life of the loan, or for the full fixed period on an ARM. It is paid in discount points; one point equals 1% of the loan amount.
- 30-year fixed: a lower rate locked in for all 30 years.
- 7/6 ARM: a lower rate for the first 7 years. After that the rate can adjust every 6 months.
Seller credit limits
Conventional guidelines cap seller-paid costs at 3% of the price when the buyer puts down less than 10%, and 6% at 10% down or more. The cards above flag any option that runs past that cap.
On the First Bank 7/6 Portfolio ARM, maximum loan-to-value is currently 90%, so the minimum down payment is 10%. Fixed-rate products allow 5% down.
Why a dollar amount doesn't equal a set rate cut
Two buyers, same house, same 1-point permanent buydown. The cost follows the loan amount, not the sale price.
| Buyer A 5% down | Buyer B 20% down |
|---|
Amortization Schedule Calculator
See your estimated monthly payment, how much goes to principal vs. interest, and how extra payments can shorten your loan.
Loan details
Taxes, insurance, HOA & PMI
Principal vs. interest by year
Mortgage Insights & Homebuyer Tips
Get clear, honest answers to the mortgage questions that matter—from how much home you can afford and the credit score you’ll need, to understanding rate locks, points, and closing costs. Based in Kansas City and the Lake of the Ozarks, Ron Cardozo helps homebuyers nationwide borrow with confidence.
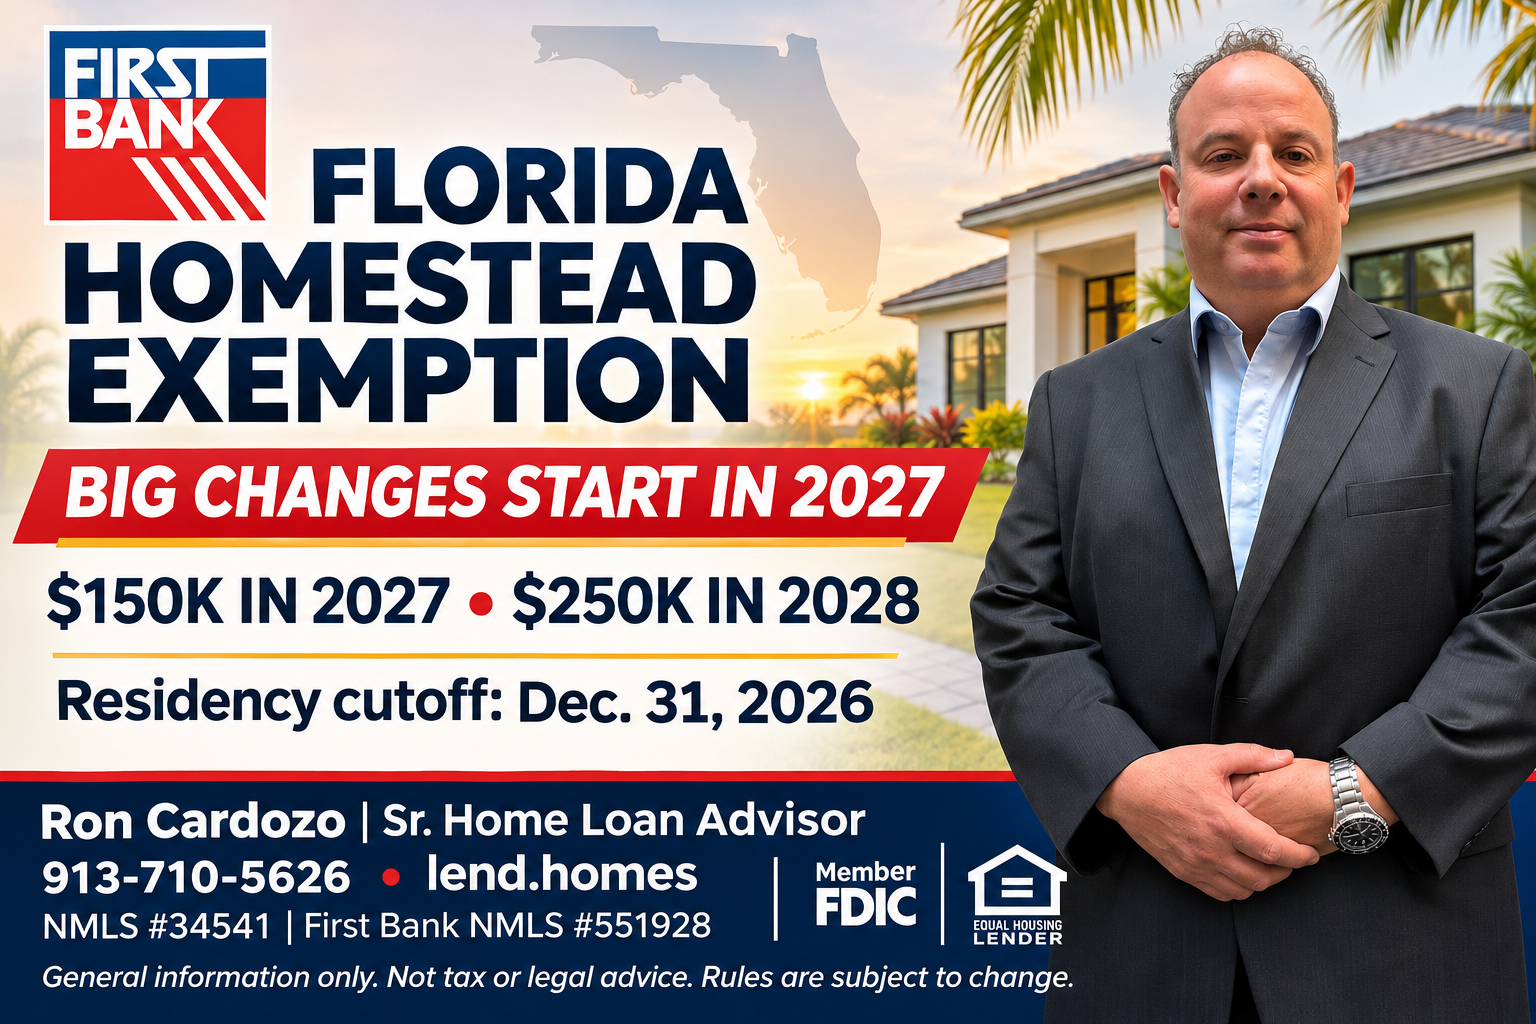
Florida's Amendment 3 Passed: What Homebuyers Need to Know Before December 31
Florida’s homestead exemption may increase to $150K in 2027 and $250K in 2028 for eligible residents. The Dec. 31, 2026 residency cutoff may matter. Details may change. Not tax advice. 913-710-5626 | ... ...more
Homebuying & Mortgage Guide
November 15, 2026
Tapping Your Home Equity: What You Need to Know About a Cash-Out Refinance
Thinking about tapping your home equity? Learn how a cash-out refinance works, timing rules, delayed financing, and what to have ready, with Ron Cardozo. ...more
Homebuying & Mortgage Guide
November 11, 2026•4 min read
Fannie Mae, Freddie Mac, or a Bank Portfolio? How Second Home Loans Compare
Fannie Mae, Freddie Mac, or a Federal Home Loan Bank loan? See how second home financing compares on down payment, underwriting, pricing, and rental income. ...more
Homebuying & Mortgage Guide
November 11, 2026•5 min read
Keeping Your Current Home as a Rental? Fannie Mae's New Departing Residence Rules Explained
Buying a new home and renting out your current one? Fannie Mae’s updated guidelines now use market rent, not a lease, to help you qualify. Here’s how the new rules work. ...more
Homebuying & Mortgage Guide
November 11, 2026•5 min read
Keep Your 3% Rate, Buy Your Dream Home
Have a 2% or 3% mortgage rate? Learn how to keep it, use a HELOC to tap your equity, buy your next home, and turn your current house into a rental for retirement, plus Fannie Mae's new December 2026 r... ...more
Homebuying & Mortgage Guide
November 04, 2026
Your Getaway, Financed: A Smart Buyer's Guide to Second Homes
Thinking about a lake house or vacation home? Ron Cardozo explains second home down payments, qualifying, second home vs. investment property, and your financing options. ...more
Homebuying & Mortgage Guide
November 03, 2026•6 min read
CLIENT EXPERIENCES
Real Stories.
Real Results.
Real homeowners. Seamless closings. Hear directly from buyers and families who trusted Ron Cardozo to guide them through every step of their financing journey.
Ron Cardozo is an exceptional loan officer, available to address your questions at any time, day or night. His promptness and attention to detail ensure a seamless buying process. He provides comprehensive tools to help buyers understand the origins of all financial figures. I am extremely satisfied with his service.
Ron Cardozo is an exceptional loan officer, available to address your questions at any time, day or night. His promptness and attention to detail ensure a seamless buying process. He provides comprehensive tools to help buyers understand the origins of all financial figures. I am extremely satisfied with his service.
Ron and his team are professionals and worked very hard to help us out when we were in a sticky situation. He held the close date as promised and we are very excited to move into our new home. If I could add more stars I would. 10/10 service and professionalism from ALL staff.
★★★★★ 5.0 Client Rating across 450+ verified homeowner reviews • Ron Cardozo NMLS #34541 | First Bank NMLS #551928
FAST • SECURE • NATIONWIDE
Ready For Pre-Approval?
Take the decisive step toward homeownership with personalized mortgage guidance. Start your secure online pre-approval in under 15 minutes or connect directly with Ron to review your financing strategy.
Ron Cardozo NMLS #34541 | First Bank NMLS #551928 • Equal Housing Lender • Licensed Nationwide
Ron Cardozo NMLS #34541 | First Bank NMLS #551928


First Bank is an Equal Housing Lender. All mortgage loans are subject to credit and underwriting approval. Programs, interest rates, terms, and conditions are subject to change without notice. This does not represent an offer to enter into a loan agreement or a commitment to lend. Ron Cardozo (NMLS #34541) operates as an authorized Senior Loan Officer representing First Bank (NMLS #551928). All state-specific licensing documentation can be inspected via the nationwide NMLS Consumer Access repository.
© 2026 Ron Cardozo | First Bank. All rights reserved. | Equal Housing Opportunity | Privacy Policy | Terms of Service